Starting out
How to become a mortgage broker in Australia
The qualification can take a few weeks. The months after it need planning, because commission arrives after a loan settles, and the first loans settle well after you start writing them.
Tell us about your business and what you need.
The short answer
Qualify, join an aggregator, and plan for the unpaid gap.
How to become a mortgage broker in Australia: complete the Certificate IV in finance and mortgage broking (most also complete the Diploma), pass police and credit checks, join an industry association and work as a credit representative under an aggregator, the company whose credit licence, lender panel and software you work under.
Qualifications
What you need before writing a loan
- The Certificate IV in finance and mortgage broking
- The minimum education standard for giving credit assistance. No prior study is required.
- The Diploma
- What aggregators and industry associations expect in practice.
- A police check and a credit check
- Do these first if there is anything on your record.
- Industry association membership
- The Mortgage & Finance Association of Australia (MFAA) or the Finance Brokers Association of Australia (FBAA). Your aggregator will say which.
Licensing
Why most new brokers work under an aggregator
You can hold your own Australian Credit Licence or work as a credit representative under an aggregator’s licence. Nearly every new broker does the second. Your own licence means an ASIC application, your own compliance arrangements and professional indemnity cover before you have written a loan. Either way you need your own membership of the Australian Financial Complaints Authority (AFCA), the complaints scheme for credit. ASIC’s guidance for credit licensees sets out those obligations.
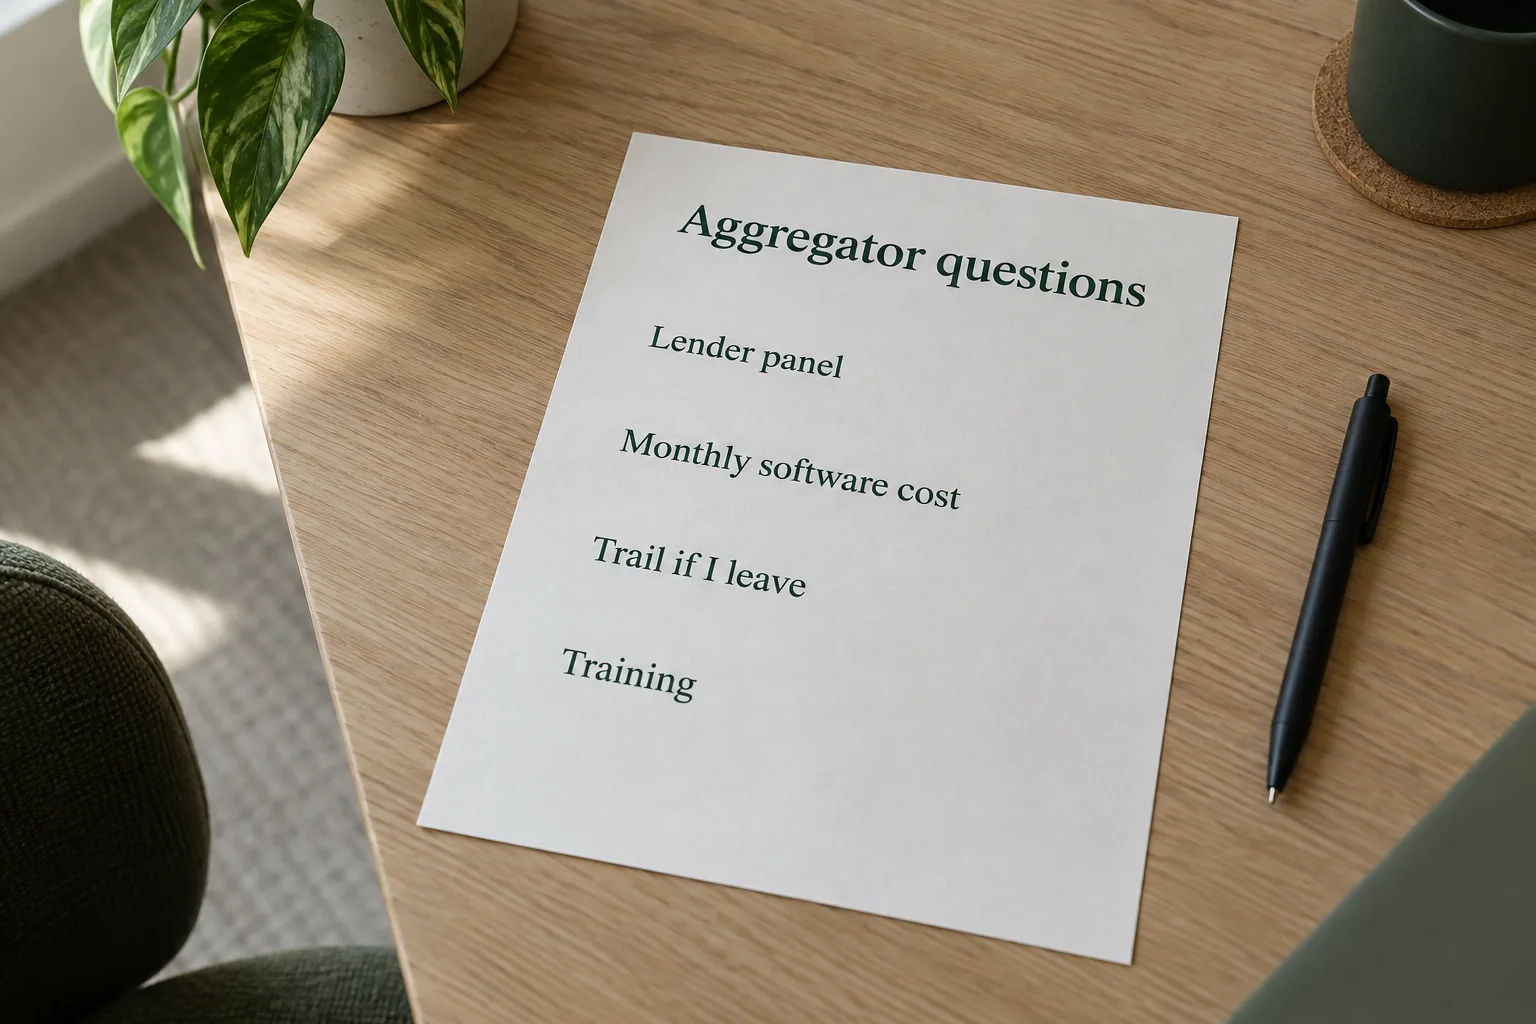
Choosing the aggregator is a big first year decision. The commission split matters less than these questions:
- Who is on the lender panel?
- A short panel limits what you can offer clients.
- What does the software cost each month?
- It is a fixed cost from day one.
- What happens to my trail if I leave?
- Trail is the ongoing commission paid while a loan stays open. Worth checking before you sign.
- What training do new brokers get?
- Ask what ongoing training is offered beyond onboarding.
The unpaid gap
Planning for months before you are paid
Commission is paid after settlement. A loan written in your first month might settle six to twelve weeks later, so plan for a long stretch without income rather than a slow start. Running out of money before the pipeline catches up is a common reason new brokers leave. Ask each aggregator what support it gives new brokers; some pay an advance, most do not.
That is also why it pays to be findable before you qualify. A Google Business Profile and reviews take time to work, so starting while you study means enquiries can arrive soon after you are able to write loans.
First clients
Where the first clients come from
Most broker business comes from referrals: accountants, buyers agents, conveyancers, real estate agents and past clients. A referral is a name, and that person will look you up before they call, so the website and profile affect whether they call.
- Create the Google Business Profile
- Searches for mortgage brokers usually include a suburb.
- Build two or three referral relationships
- Accountants and buyers agents first.
- Ask every settled client for a review
- At settlement.
The short version
Complete the qualifications, choose an aggregator on its panel, costs and trail terms, and start building a pipeline while you study so the unpaid months are shorter.
From clients
What clients say about working with spareday
“He created a stunning website for us that captures and nurtures leads with an automated email marketing system, which has filled a huge gap in the business and saved a lot of time (and money!).”
“Excellent in all facets of web design with particular expertise in SEO and email marketing. Online visibility has skyrocketed since working Reece which translates as flawless customer relations, new leads and new customers.”
“He didn’t just build me a great website, he created an easy-to-manage system that allows me to make updates myself whenever I need to. He has spared me so much time doing all of this myself!”
Official guidance
For independent background, read ASIC’s guidance for credit licensees and the official guidance on registering a business name.
Common questions
Questions people ask.
What qualification do I need to become a mortgage broker in Australia?
The Certificate IV in finance and mortgage broking is the minimum. In practice aggregators and industry associations expect the Diploma as well.
Do I need my own credit licence?
Not usually. Most new brokers work as credit representatives under an aggregator’s Australian Credit Licence.
How long before I earn anything?
Commission is paid after settlement, so a loan written in your first weeks may not pay for six to twelve weeks.
How do I choose an aggregator?
Look beyond the commission split to the lender panel, the monthly software cost, what happens to your trail if you leave and the training offered.
Where do the first clients come from?
Referrals from accountants, buyers agents, conveyancers and real estate agents, plus a Google Business Profile for your area.
How does spareday charge?
spareday quotes one price for the work your business needs, agreed in writing before anything starts. The figure depends on what the business needs, and it comes with your quote.
Who you’ll work with
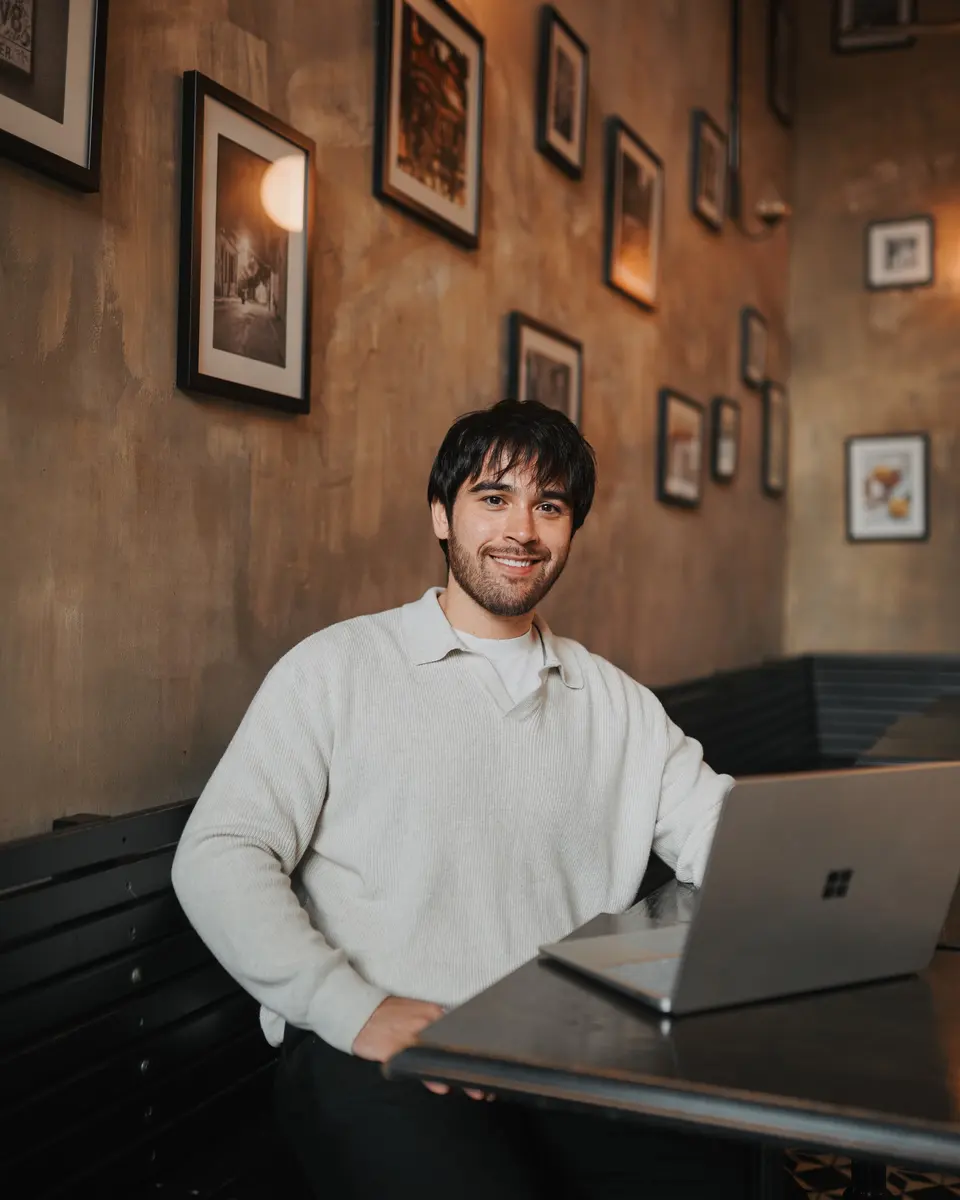
Hi, I’m Reece.
spareday is my business, based here in Newcastle. You’ll deal with me from the first review of your website, and I’m the person you talk to each month about what’s working.
Find us
spareday in Newcastle.
12 Grey Street, Wickham, Newcastle NSW 2293.
Next step
Get a free growth plan for your broking business.
spareday builds the website, Google Business Profile and enquiry setup for new brokers. Tell us your area and the clients you want to work with. We will talk through the details and send you a free growth plan, price included.
Or call 0485 017 387.